This is the single most common mental error I see people make with transfer bonuses. It looks like semantic hair-splitting, and it’s not — the two percentages describe different directions of the same trade, and they aren’t equal.
Think of it this way. A 25% bonus adds 25 miles for every 100 you send. So 100 in becomes 125 out. But if you already know you need 125 miles at the partner, you need to send in 100 — which is 20% fewer than 125, not 25% fewer. The bonus is a markup on the outgoing side, and the discount you feel is a markdown on the incoming side. Those two percentages are algebraically different.
Here’s a quick cheat sheet you can pin in your head:
| Advertised bonus | Multiplier (1 + bonus %) | Actual discount on points sent |
|---|---|---|
| 10% | 1.10 | 9.1% fewer points |
| 20% | 1.20 | 16.7% fewer points |
| 25% | 1.25 | 20% fewer points |
| 30% | 1.30 | 23.1% fewer points |
| 40% | 1.40 | 28.6% fewer points |
| 50% | 1.50 | 33.3% fewer points |
| 70% | 1.70 | 41.2% fewer points |
| 100% | 2.00 | 50% fewer points |
Notice how the gap between the two columns widens as bonuses get bigger. A 70% bonus — the kind Chase historically runs to IHG at year-end — isn’t a 70% discount on your points. It’s a 41.2% discount. That’s still enormous. But if you budgeted “70% off” in your head and only moved 30% of the points you needed, you’d come up short.
The other reason this matters: it’s how you sanity-check whether the bonus is actually beating your best alternative. If your card’s travel portal redeems points at, say, 1.25 cents each on paid flights, and the bonused transfer only pushes you from 1.5 cents of value per point to 1.7 cents, that’s the number to compare — not the headline “25%.” The percentage on the banner is a marketing metric. The cents-per-point after the bonus is the number you’re actually earning.
A Fully Worked Example: Amex to Flying Blue for Business Class to Paris
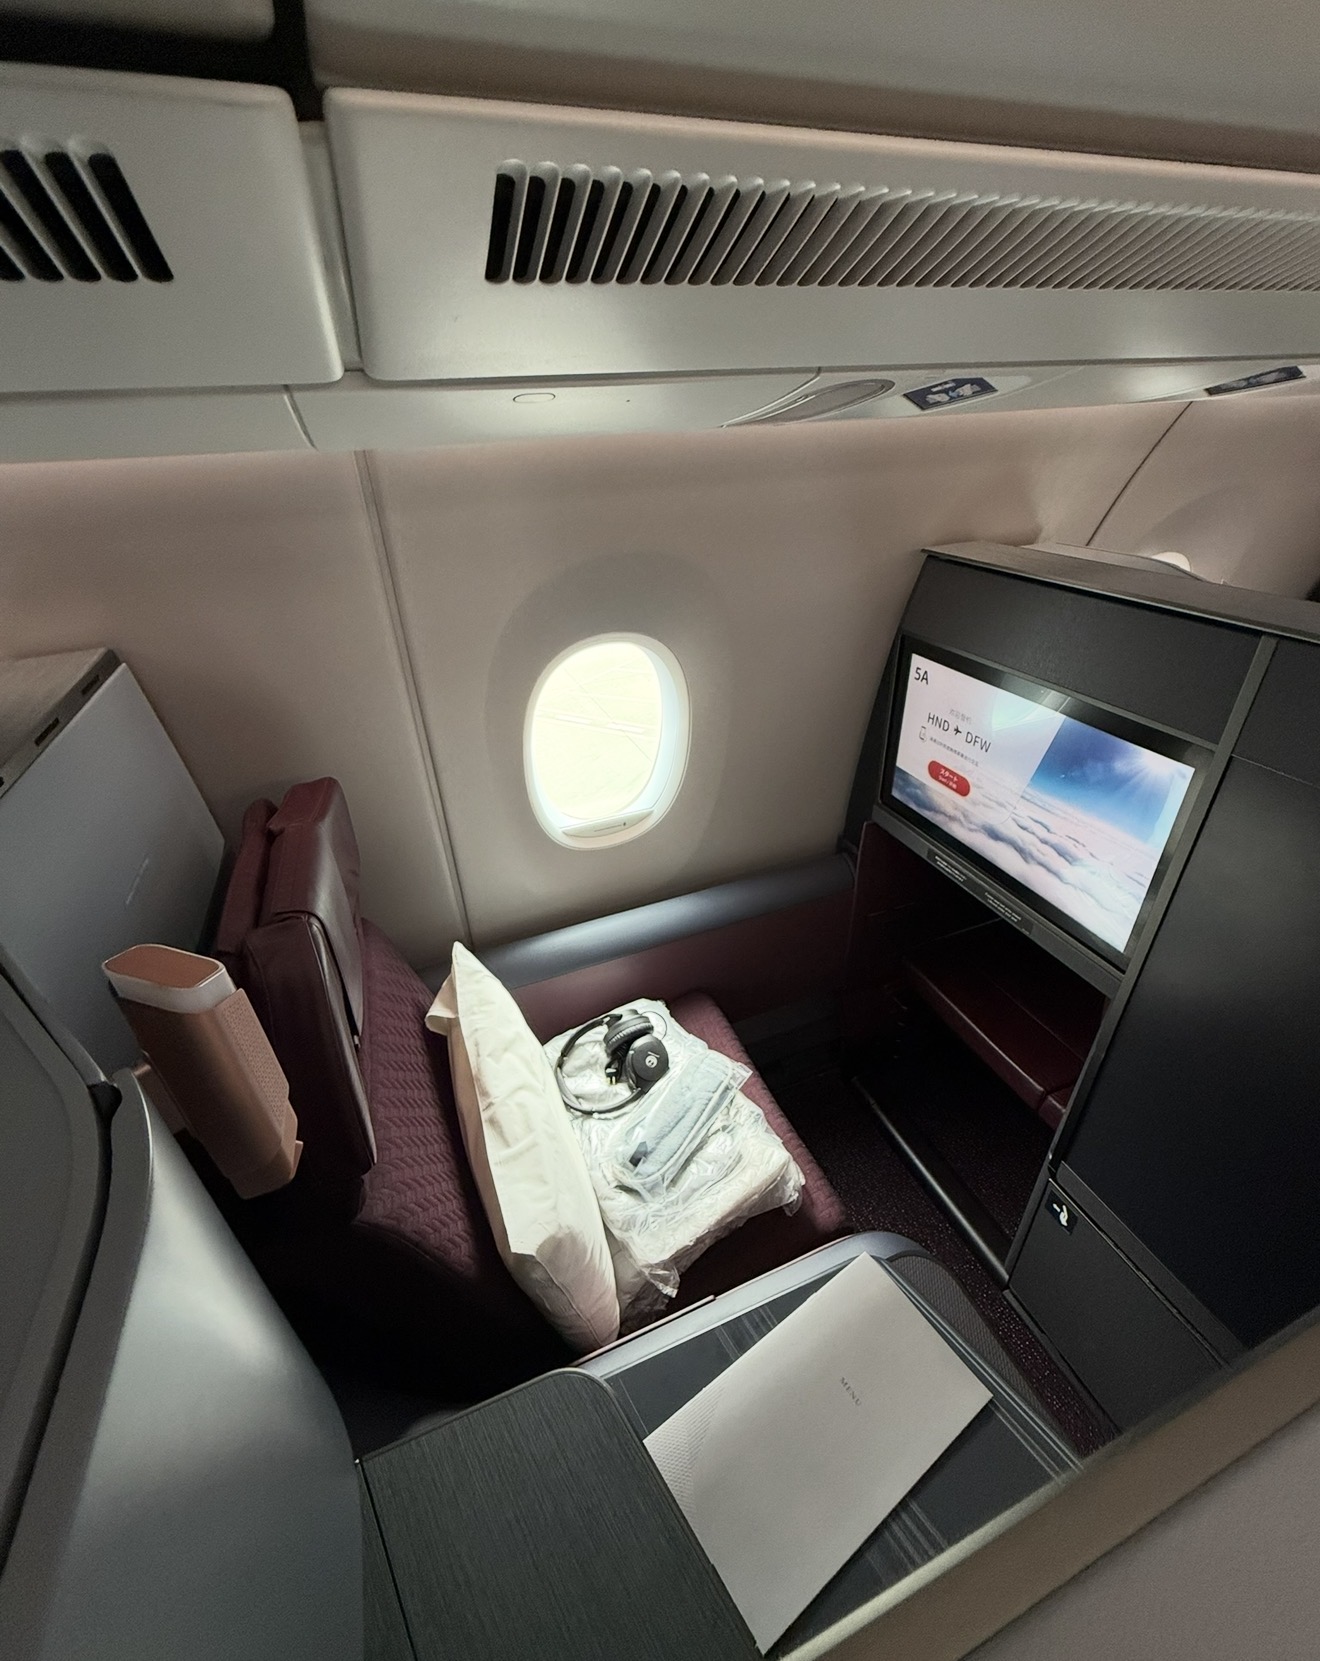
Let’s run the whole play end to end. Say I want to book a lie-flat business-class seat one-way from New York to Paris on Air France. This is one of the most-hunted redemptions in the transferable-points world for a reason: Flying Blue publishes a minimum Saver rate of 60,000 miles one-way in business class from the US to Europe, and Promo Rewards can drop it to 45,000 miles or less. Every major US transferable currency moves to Flying Blue at 1:1 — Amex, Chase, Capital One, Citi, Bilt, Wells Fargo, and Bank of America all transfer at that ratio, giving the program the broadest credit card transfer network of any major airline loyalty program.
Now assume Amex is running a 25% bonus to Flying Blue — a level Amex has hit multiple times in recent years, and one that Flying Blue sees more often than most partners. Here’s my process, step by step, exactly the way I’d do it in my own account:
- Search the seat first, before touching the transfer button. I go to flyingblue.com, log into my (already-created) Flying Blue account, and search JFK–CDG in business on my target date. If a Saver seat shows at 60,000 miles, or a Promo Reward drops it to 50,000, I take a screenshot and hold my breath — award space can vanish between searches.
- Confirm the total cost, including surcharges. Flying Blue passes carrier-imposed surcharges through, and on transatlantic business class those can run several hundred dollars. This is real cash, and it goes into the redemption’s cents-per-point math whether I like it or not.
- Run the transfer formula. For a 50,000-mile Promo Reward with a 25% Amex bonus, I need 50,000 ÷ 1.25 = 40,000 Membership Rewards points. For a 60,000-mile Saver at the same bonus, it’s 60,000 ÷ 1.25 = 48,000 points.
- Round up to the transfer minimum. Amex transfers in whole points, but I still round to the nearest thousand because I don’t want to end up 1 mile short after posting. So I’d move 48,000 points, not 47,999.
- Transfer, then book within minutes. Amex-to-Flying-Blue transfers typically arrive in a couple of minutes. Once the miles land, I complete the booking on Flying Blue immediately — I do not walk away, make coffee, or “check back tomorrow.”
The math on that transaction is genuinely great. Cash prices for one-way business class from JFK to Paris routinely run $2,500–$4,000. Moving 48,000 Amex points for a seat that would sell for, say, $3,000 puts you at roughly 6 cents per Membership Rewards point after subtracting the surcharges — well above Amex Membership Rewards’ typical valuation range and dramatically better than the roughly 1 cent per point you’d get cashing out to a statement credit. This is why the transatlantic Flying Blue redemption keeps showing up on best-value lists year after year.
And note what I did not do: I didn’t transfer 60,000 or 75,000 points “just in case.” I moved the exact number the math produced, because every extra point I send lives at the airline forever under its rules, not mine.

The One Rule That Beats Every Bonus Percentage: Only Transfer Against an Award You’ve Held
If you take away nothing else from this guide, take this: never transfer points speculatively. Bonuses reward people who already know what they want to book. Transfer to a partner only when you have a specific redemption in mind, the award space is showing live, and the partner’s price for that redemption, after the bonus, beats the next best alternative — whether that alternative is your card’s travel portal, a different transfer partner, or paying cash and earning miles.
The reason is structural. A balance held in Amex, Chase, Capital One or Citi is optionality. You can move those points to any of a dozen partners depending on what you need — Amex Membership Rewards alone transfers to around 20 airline and hotel partners, and Chase, Citi and Capital One all have similarly deep benches. The moment you transfer, that optionality collapses. The miles are locked into one program, subject to that program’s award chart, that program’s fees, and that program’s expiration policy.
The pattern that gets people burned is the “the bonus is expiring” panic transfer. A 40% bonus to Turkish Airlines Miles&Smiles is dazzling on the banner. Then you move 100,000 Citi points across, sit down to book, and discover the specific award seat you wanted was gone three days ago. Now you have 140,000 miles sitting in a program you rarely use, on an award chart that can devalue without notice, and no way back. Once points are transferred, the transaction is usually irreversible, so it is important to have a plan before moving your rewards.
The workflow that avoids this is dead simple:
- Pick a trip you actually want to take, on real dates you can commit to.
- Find live award availability in the partner program before you touch the transfer page.
- Run the formula on the exact number of miles the seat costs at that partner today.
- Transfer the exact number of points, rounded up to the transfer minimum.
- Book within minutes, before the seat is gone or the partner re-prices the award.
Everything else — hoarding miles at a partner for a “someday” trip, moving points because the bonus is “the highest we’ve ever seen,” speculating on a redemption you’ll figure out later — is where the losses happen. If you’re planning a longer trip and want to bank the reward night for a hotel around your redemption date, it’s worth pricing paid hotel rates against a points booking before you decide which currency to spend.
Why Transfers Are Irreversible (and What That Actually Costs You)
“Irreversible” is such a familiar phrase in points writing that it can wash over you. Let me spell out what it actually means for your account, because the real cost isn’t the transfer itself — it’s the risks the miles take on the moment they leave your card program.
Expiration risk. Card programs don’t expire your points as long as your account is open. Many airline programs do, particularly those outside the United States. Singapore Airlines KrisFlyer miles expire on a hard three-year clock regardless of activity. Emirates Skywards miles expire on a similar hard schedule. Programs like Aeroplan and Flying Blue reset activity clocks with any earning or redeeming, but hard-expiration programs don’t care what you do — the clock ticks. If your trip gets pushed six months and then twelve, those miles can quietly run out.
Devaluation risk. Airline programs change their award charts — sometimes overnight, often without notice. 100,000 miles that would have covered two business-class seats to Europe before a devaluation may only cover one after. A balance held at Amex, Chase, or Capital One is insulated from any single program’s changes because you can pivot to a different partner. Once you transfer, you own the devaluation risk of exactly one carrier’s award chart.
Dynamic-pricing risk. The award seat you searched five minutes ago can re-price before your transfer arrives, especially with programs like Flying Blue that use fully dynamic pricing where the same flight can be priced at very different levels day to day. Even instant transfers aren’t truly instant on every partner. Turkish Airlines is notorious for slow posting on the Citi bonus — the 40% transfer bonus from Citi to Turkish Airlines isn’t offered directly from Citi, but rather is processed after the fact by Turkish, so you won’t see the transfer bonus listed when logging into your Citi ThankYou account, and the bonus miles may take weeks to show up.
Add these up and the story is consistent: the more time between “I transferred” and “I booked,” the more ways your redemption can fall apart. Which is why the only defensible transfer is one you’re booking against a live, held, or same-day-confirmable award.
How to Judge Whether a Bonus Is Actually Worth It
Not every advertised bonus is a good deal. Some are noise. Here’s the rubric I use, in order.
1. Compare the bonused rate to your best alternative, not to zero
A 70% bonus to a low-value hotel program can still be worse than transferring nothing at all. You’re trading $20 for $8.50 with a Chase-to-IHG transfer even accounting for the 70% bonus, unless you’re redeeming IHG points at above-average value or just topping off an account for a specific booking. Compare the post-bonus cents-per-point value to what you’d get in the card’s travel portal, a different transfer partner, or a cash-plus-earning play. If the bonused rate doesn’t clearly win, skip it.
2. Ask whether the bonus is historically big or historically normal
20% is the most common transfer bonus amount, followed by 30%. Credit card transfer bonuses of 40–50% exist but are rare — a 30%+ offer is genuinely above average and worth acting on if the airline program fits your redemption plans. If a program bonuses every couple of months at 20–25%, jumping on the first 15% offer you see makes little sense unless your travel dates force your hand.
3. Don’t try to stack — bonuses don’t combine
Transfer bonuses don’t stack. Each transfer is processed against the single active bonus that applies between the specific source program and specific destination partner at the moment your transfer posts. If two currencies are both bonused to Flying Blue at the same time, you pick the better one; you don’t split the transfer to get both. The one legitimate “stack” is a card-issuer transfer bonus combined with an airline promotion on the receiving side, like Flying Blue Promo Rewards, because the airline discount is applied to the award price itself, not to the transfer.
4. Recognize which partners are worth waiting for
Some programs bonus constantly; others rarely. Flying Blue and Virgin Atlantic Flying Club get bonused most frequently, 20–30% is the most common range, and offers tend to run in predictable seasonal windows. If your redemption plan is transatlantic Air France business, patience usually pays. If it’s a program that bonuses once a year, the calculus shifts.
5. Factor in taxes, surcharges and fees before you call it a win
A 40% bonus that lets you book a business-class Paris award for 40,000 fewer miles isn’t a win if the partner passes through $700 in carrier-imposed surcharges. Your cents-per-point calculation has to subtract the cash you’re still paying. Programs known for adding heavy fees on premium-cabin awards can quietly eat a huge chunk of the bonus.
Common Bonus Sizes and What They Look Like at Real Redemption Levels
Because I find visualizing this useful, here’s the same formula run across the bonus sizes you’ll actually see, using a hypothetical 100,000-mile business-class Europe redemption and a 50,000-mile domestic economy redemption. The “points to transfer” column is the number your credit-card side needs to spend to fund the award.
| Bonus size | Points to transfer for 100,000-mile award | Points to transfer for 50,000-mile award | Points saved (100k example) |
|---|---|---|---|
| No bonus (1:1) | 100,000 | 50,000 | 0 |
| 15% | 86,957 | 43,479 | ~13,043 |
| 20% | 83,334 | 41,667 | ~16,666 |
| 25% | 80,000 | 40,000 | 20,000 |
| 30% | 76,924 | 38,462 | ~23,076 |
| 40% | 71,429 | 35,715 | ~28,571 |
| 50% | 66,667 | 33,334 | ~33,333 |
| 70% | 58,824 | 29,412 | ~41,176 |
Read that table with the earlier “how much did you actually save” cheat sheet in mind. A 20% bonus saves you around 16,700 points on a 100k redemption — not 20,000. That’s still meaningful, but if you had budgeted 80,000 in your head, you’d have miscounted by nearly 3,500 points every time.
One thing this table doesn’t show — because it varies by trip — is that your best test isn’t always “which bonus is biggest.” Sometimes moving fewer points to a partner without a bonus is smarter than moving more points to one with a bonus, because the underlying award chart is better. Aeroplan’s fixed distance-and-zone chart, for example, can undercut Flying Blue’s dynamic pricing on the exact same seat, even without a bonus. Always compare the endpoint mileage cost across all partners before you fall in love with a bonus percentage.
Which Currency Should You Hold?
- Hold Amex Membership Rewards or Chase Ultimate Rewards if you want the deepest transfer partner list and the most frequent bonus activity — these two run bonus offers roughly twice as often as Capital One or Citi over the past 12 months
- Hold Capital One Miles if you value a huge transfer partner list at 1:1 and don’t mind fewer bonus events per year — the trade-off is more flexibility per unbonused transfer
- Hold Citi ThankYou if your redemption plan leans on Turkish Airlines, Flying Blue, or Avios — Citi bonuses these partners more often than most
- Skip transferring at all if you don’t have a specific redemption in mind — no bonus is big enough to fix a bad reason to move your points
Small Habits That Save Real Points
A few operational habits I’d suggest, all learned the annoying way:
- Create the loyalty account first. You cannot transfer to a program you haven’t joined. Sign up for all the major transfer partners in advance so you can move quickly when a bonus hits.
- Store partner account numbers where you can find them fast. Bonus windows close. Digging for a loyalty number while a seat evaporates is how you miss redemptions.
- Screenshot the award search before transferring. If pricing changes on you between transfer and booking, a screenshot is your evidence to argue for the original rate — sometimes airlines will honor it, sometimes they won’t, but it’s better than no leverage.
- Confirm the transfer landed before booking. Most transfers post in minutes, some take a day or two. Don’t hit “book” if the miles haven’t hit the account.
- Keep a note of bonus history for the partners you care about. If Amex has bonused Flying Blue at 25% three times in the past year, a 15% offer probably isn’t worth acting on.
None of this is exotic. It’s the difference between people who consistently pull 4–6 cents per point out of transferable currencies and people who leave miles behind on every trade. And when you do pull off a great redemption — a lie-flat seat to Europe for under 50,000 points effective, say — the natural next step is a hotel booking, where rates fluctuate enough by day that a quick price check can save real money. That’s still just points-and-miles hygiene, applied to the cash side of the trip.
Frequently Asked Questions
What is the transfer bonus formula in plain English?
Take the number of miles you need at the airline or hotel, and divide it by 1 plus the bonus percentage expressed as a decimal. If you need 60,000 miles and the bonus is 25%, that’s 60,000 ÷ 1.25 = 48,000 points to transfer. Round up to the nearest thousand to stay safe on the airline side, and never move more than the calculation calls for.
Why does a 25% bonus mean I need 20% fewer points instead of 25% fewer?
Because the 25% is a markup on the miles you receive, not a discount on the miles you send. Sending 100 with a 25% bonus gets you 125 out. But if you already needed 125 out, you only need to send 100, which is a 20% reduction from 125 — not 25%. The bonus and the discount describe the same trade from different directions and aren’t mathematically equal.
Can I reverse a transfer if my award falls through?
No. Every credit-card-to-partner transfer is one-way and permanent. Once your Membership Rewards, Ultimate Rewards, or Capital One Miles post to an airline or hotel program, they belong to that partner and follow that partner’s rules on expiration, devaluation, and use. This is why you should only transfer against a specific award you’ve held or are booking within minutes.
Do transfer bonuses stack across programs?
No. Each transfer runs against a single active bonus between one specific source program and one specific destination partner. If two of your credit-card currencies both have a bonus to the same airline, you choose the better one — you can’t split the transfer to get both. You can, however, combine a card-issuer transfer bonus with a receiving-side airline promotion like Flying Blue Promo Rewards, because those are separate discounts applied at different steps.
What’s a “good” transfer bonus percentage?
20% is the most common bonus level and 30% is the next most common. Anything at 30% or above is genuinely above average and worth acting on if the airline program lines up with your travel plans. Bonuses at 40% or higher are relatively rare and generally worth jumping on. But the percentage alone isn’t the whole picture — you still need to compare the post-bonus mileage cost against every other partner and your card’s travel portal.
Should I ever transfer speculatively to lock in a bonus?
Almost never. Speculative transfers assume you’ll find award space later, and airline award pricing, availability, and even award charts can all change before you do. The exceptions are narrow — topping off an account by a small amount for a booking you’re already holding, or a program with unusually stable pricing and no history of devaluation. For anyone still learning the ropes, the safer default is to keep points in the card program until you have a live award to book.
Do hotel transfer bonuses ever make sense?
Occasionally, but not often. Hotel transfer ratios are generally less favorable than airline ones, and the redemption values on hotel points tend to be lower per point. The one clear case is topping off a Hilton or Marriott balance to complete a specific booking you’re already committed to — or the Amex-to-Hilton path, which transfers at 1:2 baseline and can get high enough during a bonus to work for aspirational stays. For most transferable-point holders, airline transfers deliver better value.
Bottom Line
Transfer bonuses are one of the few tools that increase the value of points you’ve already earned, but the math only works if you use them for a specific award you can book right now. Learn the one-line formula, remember that a 25% bonus is really a 20% discount, and never — ever — move points to a partner speculatively. If you can hold that discipline, bonuses become a genuine advantage. If you can’t, they become the fastest way to leak thousands of miles into programs you’ll never fully use. Bookmark this page, run the calculation before every transfer, and check our current transfer bonus roundup and historical bonus tracker whenever you’re deciding whether to pull the trigger. And when the redemption pays off with a great long-haul seat — the kind of trip we cover in our business-class flight reviews — running the same care over your hotel booking keeps the whole trip on-budget.
Most people transfer points wrong. They see a flashing “25% bonus!” banner in their card portal, punch in a round number, and hit send — and quietly hand over thousands of miles they never needed to spend. The math that fixes this is one line long, and once you internalize it, you’ll never over-transfer again.
Elevate Miles Verdict
The formula is points needed ÷ (1 + bonus %) = points to transfer. A 25% bonus means you need 20% fewer points, not 25% fewer — the difference matters. Only transfer against an award you have on hold or are 100% certain you can book, because transfers are one-way and irreversible. If you don’t have a specific redemption in mind, do not transfer, no matter how big the bonus looks.
This is the evergreen explainer we send readers who ask “should I use this bonus?” — the arithmetic, the mental shortcuts, a fully worked business-class example, and the handful of rules that separate people who make money on transfer bonuses from people who bleed points. If you already know what a transfer bonus is and just want the monthly deals, jump to our current transfer bonus roundup or the historical bonus tracker to see what’s typical for the time of year.

What a Transfer Bonus Actually Is
A transfer bonus is a limited-time multiplier on the ratio at which your credit-card points convert to an airline or hotel partner. Most of the major transferable currencies — Chase Ultimate Rewards, Capital One Miles, Bilt Rewards, Citi ThankYou Points, and Amex Membership Rewards — normally transfer to partners at a 1:1 ratio, though a handful of partners deviate from that baseline. During a bonus window, that ratio temporarily improves. A 30% transfer bonus, for example, means transferring 100,000 credit card points would give you 130,000 airline miles or hotel points, so the same award redemption costs fewer of your card points.
The important word there is temporary. Bonuses are advertised as promotions with hard end dates, and they’re one of the only levers you can pull to durably increase the redemption value of points you’ve already earned. Every other lever — welcome bonuses, category multipliers, referral offers — is about the front end. Transfer bonuses are the only one that changes the exit price of a mile after you’ve already got it in your account.
Two structural facts matter before we get to the math. First, bonuses come from the transferring program, not the receiving one — that’s why you check your Amex or Chase transfer page for a live offer, not the airline’s site. Second, the promotion only applies on the way in. There is no reverse bonus, because every credit-card-to-airline transfer partnership is one-way. Once the miles land at the partner, they’re stuck there.
The costly mistake here is transferring first and searching second. Points cannot be moved back. Confirm the space on Seats.aero before you commit a balance to one program.
What that balance actually books
Earning the points is the easy part. Whether they turn into a seat depends on flight award space, which no transfer chart or earning guide will tell you. Seats.aero searches every major program at once so you can see what your balance books on real dates.
Before you book: check the award space
Search millions of award seats across airlines, and get alerts when the flights you want become available.


 +80
Free to search · alerts are paid · partner link
The Formula: Points Needed ÷ (1 + Bonus %) = Points to Transfer
Here is the entire calculation, in one line:
Points to transfer = Points you need at the partner ÷ (1 + bonus %)
That’s it. Plug the bonus in as a decimal — 20% is 0.20, 25% is 0.25, 30% is 0.30, and so on — and divide. If Aeroplan wants 75,000 miles for the business-class seat you want, and Chase is running a 20% bonus to Aeroplan, you divide 75,000 by 1.20 and get 62,500. That’s the exact number of Ultimate Rewards points you need to move.
Two production notes on that number. You almost always have to round up to the nearest thousand because most transfer interfaces require whole thousands, so in the Aeroplan example above, you’d transfer 63,000 to be safe, since you don’t want to end up 500 short of the 75,000 you need. And when you round up, that leftover 500 miles sits in the airline’s program — not yours — under their expiration rules. That’s not a disaster on a single trip, but it’s a real cost if you make a habit of it.
Why a 25% Bonus Means You Need 20% Fewer Points, Not 25%
This is the single most common mental error I see people make with transfer bonuses. It looks like semantic hair-splitting, and it’s not — the two percentages describe different directions of the same trade, and they aren’t equal.
Think of it this way. A 25% bonus adds 25 miles for every 100 you send. So 100 in becomes 125 out. But if you already know you need 125 miles at the partner, you need to send in 100 — which is 20% fewer than 125, not 25% fewer. The bonus is a markup on the outgoing side, and the discount you feel is a markdown on the incoming side. Those two percentages are algebraically different.
Here’s a quick cheat sheet you can pin in your head:
| Advertised bonus | Multiplier (1 + bonus %) | Actual discount on points sent |
|---|---|---|
| 10% | 1.10 | 9.1% fewer points |
| 20% | 1.20 | 16.7% fewer points |
| 25% | 1.25 | 20% fewer points |
| 30% | 1.30 | 23.1% fewer points |
| 40% | 1.40 | 28.6% fewer points |
| 50% | 1.50 | 33.3% fewer points |
| 70% | 1.70 | 41.2% fewer points |
| 100% | 2.00 | 50% fewer points |
Notice how the gap between the two columns widens as bonuses get bigger. A 70% bonus — the kind Chase historically runs to IHG at year-end — isn’t a 70% discount on your points. It’s a 41.2% discount. That’s still enormous. But if you budgeted “70% off” in your head and only moved 30% of the points you needed, you’d come up short.
The other reason this matters: it’s how you sanity-check whether the bonus is actually beating your best alternative. If your card’s travel portal redeems points at, say, 1.25 cents each on paid flights, and the bonused transfer only pushes you from 1.5 cents of value per point to 1.7 cents, that’s the number to compare — not the headline “25%.” The percentage on the banner is a marketing metric. The cents-per-point after the bonus is the number you’re actually earning.
A Fully Worked Example: Amex to Flying Blue for Business Class to Paris
Let’s run the whole play end to end. Say I want to book a lie-flat business-class seat one-way from New York to Paris on Air France. This is one of the most-hunted redemptions in the transferable-points world for a reason: Flying Blue publishes a minimum Saver rate of 60,000 miles one-way in business class from the US to Europe, and Promo Rewards can drop it to 45,000 miles or less. Every major US transferable currency moves to Flying Blue at 1:1 — Amex, Chase, Capital One, Citi, Bilt, Wells Fargo, and Bank of America all transfer at that ratio, giving the program the broadest credit card transfer network of any major airline loyalty program.
Now assume Amex is running a 25% bonus to Flying Blue — a level Amex has hit multiple times in recent years, and one that Flying Blue sees more often than most partners. Here’s my process, step by step, exactly the way I’d do it in my own account:
- Search the seat first, before touching the transfer button. I go to flyingblue.com, log into my (already-created) Flying Blue account, and search JFK–CDG in business on my target date. If a Saver seat shows at 60,000 miles, or a Promo Reward drops it to 50,000, I take a screenshot and hold my breath — award space can vanish between searches.
- Confirm the total cost, including surcharges. Flying Blue passes carrier-imposed surcharges through, and on transatlantic business class those can run several hundred dollars. This is real cash, and it goes into the redemption’s cents-per-point math whether I like it or not.
- Run the transfer formula. For a 50,000-mile Promo Reward with a 25% Amex bonus, I need 50,000 ÷ 1.25 = 40,000 Membership Rewards points. For a 60,000-mile Saver at the same bonus, it’s 60,000 ÷ 1.25 = 48,000 points.
- Round up to the transfer minimum. Amex transfers in whole points, but I still round to the nearest thousand because I don’t want to end up 1 mile short after posting. So I’d move 48,000 points, not 47,999.
- Transfer, then book within minutes. Amex-to-Flying-Blue transfers typically arrive in a couple of minutes. Once the miles land, I complete the booking on Flying Blue immediately — I do not walk away, make coffee, or “check back tomorrow.”
The math on that transaction is genuinely great. Cash prices for one-way business class from JFK to Paris routinely run $2,500–$4,000. Moving 48,000 Amex points for a seat that would sell for, say, $3,000 puts you at roughly 6 cents per Membership Rewards point after subtracting the surcharges — well above Amex Membership Rewards’ typical valuation range and dramatically better than the roughly 1 cent per point you’d get cashing out to a statement credit. This is why the transatlantic Flying Blue redemption keeps showing up on best-value lists year after year.
And note what I did not do: I didn’t transfer 60,000 or 75,000 points “just in case.” I moved the exact number the math produced, because every extra point I send lives at the airline forever under its rules, not mine.
The One Rule That Beats Every Bonus Percentage: Only Transfer Against an Award You’ve Held
If you take away nothing else from this guide, take this: never transfer points speculatively. Bonuses reward people who already know what they want to book. Transfer to a partner only when you have a specific redemption in mind, the award space is showing live, and the partner’s price for that redemption, after the bonus, beats the next best alternative — whether that alternative is your card’s travel portal, a different transfer partner, or paying cash and earning miles.
The reason is structural. A balance held in Amex, Chase, Capital One or Citi is optionality. You can move those points to any of a dozen partners depending on what you need — Amex Membership Rewards alone transfers to around 20 airline and hotel partners, and Chase, Citi and Capital One all have similarly deep benches. The moment you transfer, that optionality collapses. The miles are locked into one program, subject to that program’s award chart, that program’s fees, and that program’s expiration policy.
The pattern that gets people burned is the “the bonus is expiring” panic transfer. A 40% bonus to Turkish Airlines Miles&Smiles is dazzling on the banner. Then you move 100,000 Citi points across, sit down to book, and discover the specific award seat you wanted was gone three days ago. Now you have 140,000 miles sitting in a program you rarely use, on an award chart that can devalue without notice, and no way back. Once points are transferred, the transaction is usually irreversible, so it is important to have a plan before moving your rewards.
The workflow that avoids this is dead simple:
- Pick a trip you actually want to take, on real dates you can commit to.
- Find live award availability in the partner program before you touch the transfer page.
- Run the formula on the exact number of miles the seat costs at that partner today.
- Transfer the exact number of points, rounded up to the transfer minimum.
- Book within minutes, before the seat is gone or the partner re-prices the award.
Everything else — hoarding miles at a partner for a “someday” trip, moving points because the bonus is “the highest we’ve ever seen,” speculating on a redemption you’ll figure out later — is where the losses happen. If you’re planning a longer trip and want to bank the reward night for a hotel around your redemption date, it’s worth pricing paid hotel rates against a points booking before you decide which currency to spend.
Why Transfers Are Irreversible (and What That Actually Costs You)
“Irreversible” is such a familiar phrase in points writing that it can wash over you. Let me spell out what it actually means for your account, because the real cost isn’t the transfer itself — it’s the risks the miles take on the moment they leave your card program.
Expiration risk. Card programs don’t expire your points as long as your account is open. Many airline programs do, particularly those outside the United States. Singapore Airlines KrisFlyer miles expire on a hard three-year clock regardless of activity. Emirates Skywards miles expire on a similar hard schedule. Programs like Aeroplan and Flying Blue reset activity clocks with any earning or redeeming, but hard-expiration programs don’t care what you do — the clock ticks. If your trip gets pushed six months and then twelve, those miles can quietly run out.
Devaluation risk. Airline programs change their award charts — sometimes overnight, often without notice. 100,000 miles that would have covered two business-class seats to Europe before a devaluation may only cover one after. A balance held at Amex, Chase, or Capital One is insulated from any single program’s changes because you can pivot to a different partner. Once you transfer, you own the devaluation risk of exactly one carrier’s award chart.
Dynamic-pricing risk. The award seat you searched five minutes ago can re-price before your transfer arrives, especially with programs like Flying Blue that use fully dynamic pricing where the same flight can be priced at very different levels day to day. Even instant transfers aren’t truly instant on every partner. Turkish Airlines is notorious for slow posting on the Citi bonus — the 40% transfer bonus from Citi to Turkish Airlines isn’t offered directly from Citi, but rather is processed after the fact by Turkish, so you won’t see the transfer bonus listed when logging into your Citi ThankYou account, and the bonus miles may take weeks to show up.
Add these up and the story is consistent: the more time between “I transferred” and “I booked,” the more ways your redemption can fall apart. Which is why the only defensible transfer is one you’re booking against a live, held, or same-day-confirmable award.
How to Judge Whether a Bonus Is Actually Worth It
Not every advertised bonus is a good deal. Some are noise. Here’s the rubric I use, in order.
1. Compare the bonused rate to your best alternative, not to zero
A 70% bonus to a low-value hotel program can still be worse than transferring nothing at all. You’re trading $20 for $8.50 with a Chase-to-IHG transfer even accounting for the 70% bonus, unless you’re redeeming IHG points at above-average value or just topping off an account for a specific booking. Compare the post-bonus cents-per-point value to what you’d get in the card’s travel portal, a different transfer partner, or a cash-plus-earning play. If the bonused rate doesn’t clearly win, skip it.
2. Ask whether the bonus is historically big or historically normal
20% is the most common transfer bonus amount, followed by 30%. Credit card transfer bonuses of 40–50% exist but are rare — a 30%+ offer is genuinely above average and worth acting on if the airline program fits your redemption plans. If a program bonuses every couple of months at 20–25%, jumping on the first 15% offer you see makes little sense unless your travel dates force your hand.
3. Don’t try to stack — bonuses don’t combine
Transfer bonuses don’t stack. Each transfer is processed against the single active bonus that applies between the specific source program and specific destination partner at the moment your transfer posts. If two currencies are both bonused to Flying Blue at the same time, you pick the better one; you don’t split the transfer to get both. The one legitimate “stack” is a card-issuer transfer bonus combined with an airline promotion on the receiving side, like Flying Blue Promo Rewards, because the airline discount is applied to the award price itself, not to the transfer.
4. Recognize which partners are worth waiting for
Some programs bonus constantly; others rarely. Flying Blue and Virgin Atlantic Flying Club get bonused most frequently, 20–30% is the most common range, and offers tend to run in predictable seasonal windows. If your redemption plan is transatlantic Air France business, patience usually pays. If it’s a program that bonuses once a year, the calculus shifts.
5. Factor in taxes, surcharges and fees before you call it a win
A 40% bonus that lets you book a business-class Paris award for 40,000 fewer miles isn’t a win if the partner passes through $700 in carrier-imposed surcharges. Your cents-per-point calculation has to subtract the cash you’re still paying. Programs known for adding heavy fees on premium-cabin awards can quietly eat a huge chunk of the bonus.
Common Bonus Sizes and What They Look Like at Real Redemption Levels
Because I find visualizing this useful, here’s the same formula run across the bonus sizes you’ll actually see, using a hypothetical 100,000-mile business-class Europe redemption and a 50,000-mile domestic economy redemption. The “points to transfer” column is the number your credit-card side needs to spend to fund the award.
| Bonus size | Points to transfer for 100,000-mile award | Points to transfer for 50,000-mile award | Points saved (100k example) |
|---|---|---|---|
| No bonus (1:1) | 100,000 | 50,000 | 0 |
| 15% | 86,957 | 43,479 | ~13,043 |
| 20% | 83,334 | 41,667 | ~16,666 |
| 25% | 80,000 | 40,000 | 20,000 |
| 30% | 76,924 | 38,462 | ~23,076 |
| 40% | 71,429 | 35,715 | ~28,571 |
| 50% | 66,667 | 33,334 | ~33,333 |
| 70% | 58,824 | 29,412 | ~41,176 |
Read that table with the earlier “how much did you actually save” cheat sheet in mind. A 20% bonus saves you around 16,700 points on a 100k redemption — not 20,000. That’s still meaningful, but if you had budgeted 80,000 in your head, you’d have miscounted by nearly 3,500 points every time.
One thing this table doesn’t show — because it varies by trip — is that your best test isn’t always “which bonus is biggest.” Sometimes moving fewer points to a partner without a bonus is smarter than moving more points to one with a bonus, because the underlying award chart is better. Aeroplan’s fixed distance-and-zone chart, for example, can undercut Flying Blue’s dynamic pricing on the exact same seat, even without a bonus. Always compare the endpoint mileage cost across all partners before you fall in love with a bonus percentage.
Which Currency Should You Hold?
- Hold Amex Membership Rewards or Chase Ultimate Rewards if you want the deepest transfer partner list and the most frequent bonus activity — these two run bonus offers roughly twice as often as Capital One or Citi over the past 12 months
- Hold Capital One Miles if you value a huge transfer partner list at 1:1 and don’t mind fewer bonus events per year — the trade-off is more flexibility per unbonused transfer
- Hold Citi ThankYou if your redemption plan leans on Turkish Airlines, Flying Blue, or Avios — Citi bonuses these partners more often than most
- Skip transferring at all if you don’t have a specific redemption in mind — no bonus is big enough to fix a bad reason to move your points
Small Habits That Save Real Points
A few operational habits I’d suggest, all learned the annoying way:
- Create the loyalty account first. You cannot transfer to a program you haven’t joined. Sign up for all the major transfer partners in advance so you can move quickly when a bonus hits.
- Store partner account numbers where you can find them fast. Bonus windows close. Digging for a loyalty number while a seat evaporates is how you miss redemptions.
- Screenshot the award search before transferring. If pricing changes on you between transfer and booking, a screenshot is your evidence to argue for the original rate — sometimes airlines will honor it, sometimes they won’t, but it’s better than no leverage.
- Confirm the transfer landed before booking. Most transfers post in minutes, some take a day or two. Don’t hit “book” if the miles haven’t hit the account.
- Keep a note of bonus history for the partners you care about. If Amex has bonused Flying Blue at 25% three times in the past year, a 15% offer probably isn’t worth acting on.
None of this is exotic. It’s the difference between people who consistently pull 4–6 cents per point out of transferable currencies and people who leave miles behind on every trade. And when you do pull off a great redemption — a lie-flat seat to Europe for under 50,000 points effective, say — the natural next step is a hotel booking, where rates fluctuate enough by day that a quick price check can save real money. That’s still just points-and-miles hygiene, applied to the cash side of the trip.
Frequently Asked Questions
What is the transfer bonus formula in plain English?
Take the number of miles you need at the airline or hotel, and divide it by 1 plus the bonus percentage expressed as a decimal. If you need 60,000 miles and the bonus is 25%, that’s 60,000 ÷ 1.25 = 48,000 points to transfer. Round up to the nearest thousand to stay safe on the airline side, and never move more than the calculation calls for.
Why does a 25% bonus mean I need 20% fewer points instead of 25% fewer?
Because the 25% is a markup on the miles you receive, not a discount on the miles you send. Sending 100 with a 25% bonus gets you 125 out. But if you already needed 125 out, you only need to send 100, which is a 20% reduction from 125 — not 25%. The bonus and the discount describe the same trade from different directions and aren’t mathematically equal.
Can I reverse a transfer if my award falls through?
No. Every credit-card-to-partner transfer is one-way and permanent. Once your Membership Rewards, Ultimate Rewards, or Capital One Miles post to an airline or hotel program, they belong to that partner and follow that partner’s rules on expiration, devaluation, and use. This is why you should only transfer against a specific award you’ve held or are booking within minutes.
Do transfer bonuses stack across programs?
No. Each transfer runs against a single active bonus between one specific source program and one specific destination partner. If two of your credit-card currencies both have a bonus to the same airline, you choose the better one — you can’t split the transfer to get both. You can, however, combine a card-issuer transfer bonus with a receiving-side airline promotion like Flying Blue Promo Rewards, because those are separate discounts applied at different steps.
What’s a “good” transfer bonus percentage?
20% is the most common bonus level and 30% is the next most common. Anything at 30% or above is genuinely above average and worth acting on if the airline program lines up with your travel plans. Bonuses at 40% or higher are relatively rare and generally worth jumping on. But the percentage alone isn’t the whole picture — you still need to compare the post-bonus mileage cost against every other partner and your card’s travel portal.
Should I ever transfer speculatively to lock in a bonus?
Almost never. Speculative transfers assume you’ll find award space later, and airline award pricing, availability, and even award charts can all change before you do. The exceptions are narrow — topping off an account by a small amount for a booking you’re already holding, or a program with unusually stable pricing and no history of devaluation. For anyone still learning the ropes, the safer default is to keep points in the card program until you have a live award to book.
Do hotel transfer bonuses ever make sense?
Occasionally, but not often. Hotel transfer ratios are generally less favorable than airline ones, and the redemption values on hotel points tend to be lower per point. The one clear case is topping off a Hilton or Marriott balance to complete a specific booking you’re already committed to — or the Amex-to-Hilton path, which transfers at 1:2 baseline and can get high enough during a bonus to work for aspirational stays. For most transferable-point holders, airline transfers deliver better value.
Bottom Line
Transfer bonuses are one of the few tools that increase the value of points you’ve already earned, but the math only works if you use them for a specific award you can book right now. Learn the one-line formula, remember that a 25% bonus is really a 20% discount, and never — ever — move points to a partner speculatively. If you can hold that discipline, bonuses become a genuine advantage. If you can’t, they become the fastest way to leak thousands of miles into programs you’ll never fully use. Bookmark this page, run the calculation before every transfer, and check our current transfer bonus roundup and historical bonus tracker whenever you’re deciding whether to pull the trigger. And when the redemption pays off with a great long-haul seat — the kind of trip we cover in our business-class flight reviews — running the same care over your hotel booking keeps the whole trip on-budget.