A $795 Sapphire Reserve fee or an $895 Platinum fee hitting your statement starts a 30-day clock, not a decision. Work it in this order: ask for a retention offer, then product-change, and close only if no path keeps your points alive. Cardholders report Reserve retention credits of $100 to $400 and Platinum offers of 20,000 to 50,000 Membership Rewards points, and the product change is what protects your balance and your account age if the answer is no.
Elevate Miles Verdict
Never close a premium card as your first move, and almost never as your second. Ask for a retention offer the week the fee posts, and if it is weak, product-change into a cheaper card in the same family so your points, your credit line and your account history all survive. Closing is the right answer only when you hold a second card in the same currency, have already moved the balance, and genuinely want the account gone.
This is the part of the hobby nobody plans for. You read a review, you applied, you got the bonus, and eighteen months later a number you did not budget for lands on your statement. Both of the biggest premium cards repriced inside the last two years: the Sapphire Reserve went from $550 to $795, with existing cardholders billed the higher fee on renewals from October 26, 2025, and the Platinum went to $895, hitting new applicants from September 18, 2025 and existing accounts at their first renewal on or after January 2, 2026. That means renewals are still rolling through 2026 and into 2027, and a lot of readers are seeing the new number for the first time right now.

The 30-Day Clock That Starts When the Fee Posts
Every issuer gives you a short window to undo the charge, and the windows are not the same. Get this part wrong and the decision gets made for you.
Chase will typically refund the fee in full if you cancel or product-change within 30 days of the fee being billed, and does not generally prorate beyond that window. There is a genuine disagreement in the data here worth knowing about: several issuer-policy roundups say a downgrade processed more than 30 to 41 days out can still produce a prorated refund, while Chase-facing reporting and reader reports say a late closure gets you nothing at all. Treat 30 days as the real deadline and anything after it as a bonus you might not get.
American Express is the cleanest and the most generous if you use it correctly. Amex’s cardmember agreement language says the fee is refunded if you notify Amex you are voluntarily closing within 30 days of the closing date of the billing statement on which the fee appears, and that after that period the fee is non-refundable. Note the trigger: it is the statement closing date, not the day the charge appeared, which usually buys you more time than people assume. The important asymmetry is that a product change is prorated at any point in the year, so a Platinum holder who missed the cancellation window entirely can still downgrade in month seven and get roughly five months of fee back.
Capital One is the inconsistent one. The commonly reported window is about 39 days from billing to cancel and get refunded, downgrades inside that window do not reliably produce a partial refund, and in some cases Capital One simply declines to refund a fee once charged. Citi runs roughly 37 days with no proration afterward. If you are holding a Citi or Capital One premium card, do not wait to see how the year goes.
One more timing point that costs people real money: the fee posting and your benefit year are two different calendars. The Reserve’s $300 travel credit runs on your cardmember anniversary year, so if you are going to close, trigger it first on a flight you were booking anyway rather than leaving $300 on the table. Same logic for the Platinum’s semi-annual Fine Hotels + Resorts credit, which is worth up to $300 back twice a calendar year on prepaid FHR or Hotel Collection bookings through Amex Travel. Our breakdown of how those credits stack at a Four Seasons shows what a single well-timed booking recovers.
 elevatemiles

Newsletter
Travel using fewer points with advanced strategies
I send what is actually worth acting on: new transfer bonuses, award space worth booking, and the mistakes that quietly cost people their points.
Free forever · unsubscribe in one click
Step One: Ask for a Retention Offer Before You Do Anything Else
Retention offers are not guaranteed, not published, and not consistent. They are also free to ask for, and the reported outcomes on both headline cards are large enough that skipping the call is the single most expensive habit in this hobby.
What Chase is reportedly giving Sapphire Reserve holders
Since the fee increase, reported Reserve retention offers cluster at $100 as the most common outcome, with $150 and $300 showing up and a handful of $400 statement credits documented, often with no spending requirement attached. A $400 credit against a $795 fee is a 50% discount for one phone call. Many cardholders are offered nothing, so go in expecting $0 and treat anything above it as found money.
There is one offer to refuse. Chase reps have been floating the option to pay the annual fee with Ultimate Rewards at 1.25 cents each, which works out to roughly 63,600 points to cover $795. That is a bad trade for anyone reading this site, because those same points transfer to partners or book through Points Boost hotels at up to 2 cents each. You are handing over about $1,270 of redemption value to settle a $795 bill.
What Amex is reportedly giving Platinum holders
Documented 2026 Platinum outcomes include 20,000 Membership Rewards points after $3,000 in spend over three months, 50,000 points after $3,000 in spend, and in other reports a flat statement credit with no spend requirement. Amex’s retention team is reachable by phone or through chat, and the chat team keeps weekday business hours while the phone line runs later.
Amex has its own version of the bad offer, and it is showing up more often: redeem Membership Rewards to pay the fee at an “elevated” 1 cent per point instead of the standard 0.6 cents. Covering $895 that way costs 89,500 points. Membership Rewards are worth well north of 1.5 cents each transferred to partners, so the “favor” costs you several hundred dollars. Decline it and ask whether anything else is available on the account.
The script that works is short and honest: the fee posted, you are deciding whether the card still makes sense, and are there any retention offers on the account. Do not open with the word “cancel” in an automated phone tree, because the system can route you straight into a closure. Get to a human first.
Then run the arithmetic before you accept. The test is whether the credits you will genuinely use, plus the offer’s value, exceed the fee. A 30,000-point offer requiring $3,000 of incremental spend is roughly $450 at 1.5 cents per point, which is enough to flip a borderline keep and not enough to rescue a card you have stopped using. Half-used credits are worth $0 no matter what the marketing page says they are worth.
Step Two: Product-Change, Because That Is What Protects the Points
A product change swaps the card on an existing account instead of opening or closing one. Capital One’s own explainer puts it plainly: the existing credit line is transferred, the card and account number typically stay the same, no new account is opened and no current account is closed, and because there is no new account there is typically no hard inquiry. Chase downgrades keep your card number, credit limit and APR, with a new expiration date and security code, and the replacement card generally arrives within 7 to 10 business days.
Two universal conditions apply. You generally need the account open at least 12 months before an issuer will process a change, and a product change never pays a welcome bonus on the destination card.
Chase: the $795 to $95 move, and the Hyatt trap inside it
The Sapphire Reserve downgrades to the Chase Sapphire Preferred at $95, or to a Freedom Unlimited or Freedom Flex at $0. The Preferred keeps transfer partners, Chase Travel access and a $100 annual hotel credit on Chase Travel stays, and drops Priority Pass, the $300 travel credit and the Edit credits.
Here is the cost most downgrade guides still leave out. As of October 1, 2026, Ultimate Rewards transfer to World of Hyatt at 4:3 from the Sapphire Preferred, Ink Business Preferred and the legacy Ink Plus and Corporate Flex cards, while the Sapphire Reserve and Sapphire Reserve for Business keep 1:1. Anyone approved for a Preferred on or after June 15, 2026 has been at 4:3 from day one. In practice, a 25,000-point Hyatt night costs 25,000 Ultimate Rewards from a Reserve and about 34,000 from a Preferred, because transfers move in 1,000-point increments. If Hyatt is the backbone of how you redeem — the case our Grand Hyatt Baha Mar breakdown walks through in detail — the Reserve’s $700 fee premium is buying a 33% better transfer rate, and the downgrade is more expensive than it looks.
If those numbers no longer work for the balance you actually hold, Roame scans 25 programs across a full year of dates and will show you which currency still reaches the trip you had planned.
Downgrading all the way to a Freedom card is the $0 answer, and it comes with a specific catch: Freedom cards earn Ultimate Rewards but cannot transfer them to partners. Your balance survives, your account age survives, and your points quietly become portal-and-cash-back points unless you hold a Sapphire or Ink Preferred to pool them into. For a reader whose only Chase card is the Reserve, that is the difference between a 2-cent transfer and a 1-cent redemption.

Amex: there is no free exit from the Platinum
Amex restricts product changes to cards inside the same family. From the Platinum, that means the Amex Gold at $325 or the Classic Green at $150, and nothing at $0. The Classic Green closed to new applicants on July 23, 2026 but has remained available as a Platinum downgrade target, which makes it the cheapest way to keep a personal Membership Rewards card open.
The trap is Amex’s once-per-lifetime bonus language. Product-changing into a Gold you have never held means you will not be able to earn the Gold’s welcome offer later, and that offer has recently run as high as 100,000 points after $8,000 of spend in six months. If you have never held the Gold and you can still use the Platinum for another cycle, applying for the Gold as a fresh card and downgrading the Platinum afterward is usually worth more than the downgrade alone. Amex also warns that downgrading within 12 months of receiving an upgrade bonus can put your account in bad standing, so do not treat a bonus-paying upgrade as a short-term play.
If you want zero annual fees and still want transferable Membership Rewards, the standard answer is the no-annual-fee Blue Business Plus, which earns 2 points per dollar on the first $50,000 of purchases each calendar year and then 1 point per dollar. Amex’s own cancellation FAQ also names a Membership Rewards-eligible checking account as something that keeps a balance alive, which is a path most guides never mention.
Capital One and Citi
The Venture X runs $395 and downgrades to the Capital One Venture at $95, the VentureOne at $0, or in some cases a Quicksilver. Capital One is explicit that these are decided account by account, so the option you want may not be offered. Time it deliberately: the Venture X deposits 10,000 anniversary miles every year starting at your first anniversary, and its $300 credit is restricted to Capital One Travel bookings and expires at your next anniversary. Downgrade after the miles post and after the credit is spent, not before.
Citi keeps it simpler: change within the ThankYou family and your points stay attached to a participating account. Convert to a card that does not participate in ThankYou Rewards and Citi’s own program terms treat it the same way as a closure.
| Issuer | Full-refund window | Cheaper downgrade targets | If you close instead |
|---|---|---|---|
| Chase | 30 days from the fee posting, cancel or downgrade; no reliable proration after | Sapphire Preferred $95; Freedom Unlimited or Freedom Flex $0 | Points sit with the closed account; Chase says you no longer have them, so move them first |
| Amex | 30 days from the closing date of the statement showing the fee; downgrades prorate any time | Gold $325; Classic Green $150; no $0 option in the family | Closing your last linked Membership Rewards product forfeits that balance immediately |
| Capital One | About 39 days, applied inconsistently; sometimes refused outright | Venture $95; VentureOne $0; Quicksilver $0, offered case by case | Unredeemed miles are lost at closure |
| Citi | About 37 days, no proration after | Any participating ThankYou card | Citi’s terms give 60 days to redeem after closing or converting to a non-participating account |
Every one of these also requires the account to be roughly 12 months old before the issuer will process a change, and none of them pays a welcome bonus on the new product.
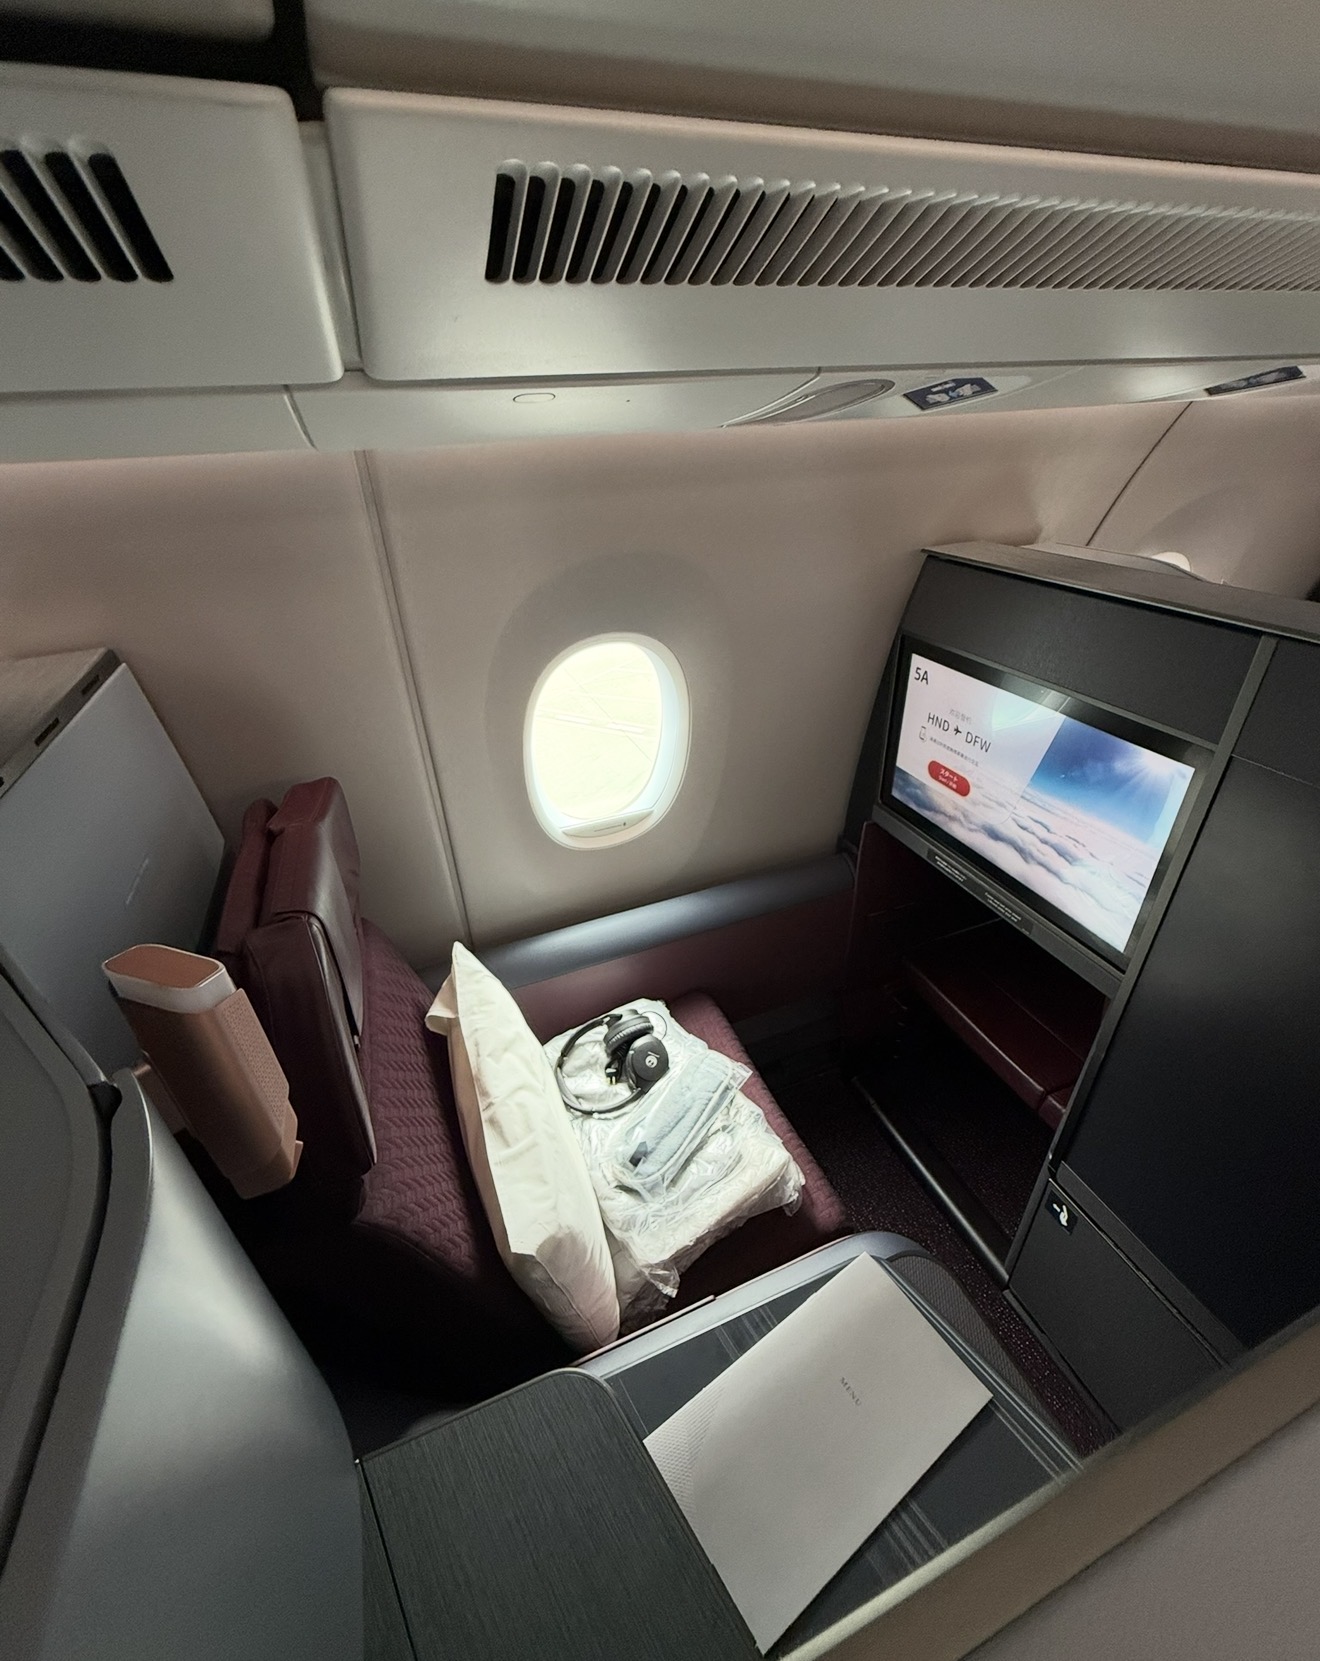
What that balance actually books
Earning the points is the easy part. Whether they become a seat depends on flight award space, so check it before you transfer.


 +80
Free to search · partner link
What Closing Actually Costs You
Three separate things are at risk when you close, and only one of them is obvious.
The points. American Express states on its own Membership Rewards cancellation page that if you cancel your Membership Rewards account and do not have another eligible card or checking account, unredeemed points are forfeited immediately. There are narrow exceptions — a last linked Corporate Card may carry up to 30 days, and New York cardmembers get up to 90 days by calling — but the default is instant. Chase’s own rewards page says points do not expire while the account is open, and that if you close before redeeming or transferring, you no longer have those points. Third-party guides widely quote a 30-day grace period after a Chase closure; Chase’s consumer page promises nothing of the kind for a voluntary closure, so do not bet a six-figure balance on it.
There is a brand-new wrinkle on the Amex side that will catch people out. As of an October 2026 program-terms amendment, points earned on newly opened U.S. cards go into their own Rewards Account rather than pooling automatically with your existing balance. You can still combine them through Manage Connections on the site or app, or by calling, but if you skip that step and later close the new card, that account’s points can be forfeited even though you still hold another Membership Rewards card. Seeing two cards under one login does not mean the rewards accounts are linked. Check before you close anything.
The safest sequence before any closure is: pool or link the balances, confirm the combined total, then move points only against a redemption you actually intend to book. Speculative transfers swap a balance that cannot expire for one that can. The exception worth making is a live promotion — if there is a bonus running on the partner you were already going to use, check the current transfer bonus tracker before you pull the trigger. And if you are about to move a large balance and want to know whether a different program reaches the same seat for less, Roame’s subscription search is built for exactly that comparison.
Your 5/24 count. This one is widely misunderstood in both directions. Chase counts personal cards you have opened in the last 24 months regardless of whether they are still open, so closing a card does not buy back a slot. A product change generally does not add to your count either, unless it involves a hard pull or a new account number. Chase has never published the rule, and it is still being enforced in 2026.
Your credit profile. Closing removes that credit line from your total available credit, which raises utilization on everything else, and it eventually trims the average age of your accounts. A downgrade keeps both intact, which is the quiet reason experienced cardholders almost never close a long-held account.
The Downgrade-and-Reapply Play Is Dead at Chase
Plenty of guides still describe the “Sapphire switcheroo”: downgrade your Sapphire to a Freedom, wait out the 48-month clock, reapply, collect another six-figure bonus. That strategy no longer works the way it is written.
Chase eliminated the 48-month rule alongside the June 2025 Reserve refresh, and on January 22, 2026 it updated the Sapphire terms again. The current application language reads that the card is unavailable to you if you currently have one open, that the new cardmember bonus may not be available if you previously held the card or received a bonus for it, and that Chase will also consider how many cards you have opened and closed. The practical translation: one bonus per Sapphire product, effectively for life, with the upside that you can now hold the Preferred and the Reserve at the same time and earn each card’s bonus once. The Sapphire Reserve for Business is treated as a separate product.
So closing a Sapphire to “reset the clock” accomplishes nothing except losing your account history, and in the worst case your points. Chase now shows an eligibility pop-up during the application that tells you whether a bonus is available before you take a hard pull, which is the only reliable way to check your own situation.
The equivalent restrictions elsewhere: Amex’s once-per-lifetime rule means having held a card ever can block its welcome offer, and its family rules mean holding a Platinum can affect your eligibility for Gold and Green offers. Capital One’s own terms state you are not eligible for the Venture bonus if you have received a new cardmember bonus on the Venture or Venture X in the past 48 months. None of these clocks are reset by closing an account.
The Order of Operations on Fee Day
- Note the date the fee posted and the statement closing date. That is your refund deadline, and it is 30 to 39 days depending on the issuer
- Spend every credit that is already live. Chase’s $300 travel credit, the Edit credits, Amex’s semi-annual FHR credit, Capital One’s $300 portal credit. A credit you forfeit is a straight loss against the fee
- Add up what you actually used last year, not what the issuer claims the card is worth. If realistic usage is under half the fee, the card is a subscription, not a tool
- Call or chat for a retention offer. Get to a human before using the word cancel. Decline any offer to pay the fee with points at 1 to 1.25 cents each
- If the offer is weak, name your downgrade target and confirm whether the annual fee will be refunded, prorated, or kept
- Before any closure, link and pool your rewards accounts, confirm the combined balance, and move the points only if you have a redemption in mind
- Close only if you hold another card in the same currency and have a reason the account itself needs to go
One case where keeping the card genuinely wins: if your redemptions lean on the Reserve’s Edit and Points Boost stack, the fee can come back on a single booking. Our walkthrough of stacking the Edit and Select Hotels credits at Montage Palmetto Bluff shows roughly $800 off one two-night reservation, which is more than the entire annual fee in a single stay.
Which Card Is Right for You?
- Keep the Sapphire Reserve if Hyatt is your main redemption program — it is the only personal Chase card still transferring 1:1 after October 1, 2026, and you can pool points from your other Chase cards into it
- Downgrade to the Sapphire Preferred if you want transfer partners and travel protections for $95 and you can live with the 4:3 Hyatt ratio
- Downgrade the Platinum to the Classic Green if you only need a cheap home for your Membership Rewards balance and you have already held the Gold
- Add a Blue Business Plus if you want a $0 way to keep Membership Rewards transferable permanently, independent of any premium card
- Close only if you hold a second card in the same currency, the points are already pooled there, and the account itself no longer serves a purpose
Frequently Asked Questions
Does downgrading a credit card hurt my credit score?
Generally no. A product change moves your existing credit line to a different card without opening or closing an account, which preserves your account age and your available credit, and it typically does not involve a hard inquiry. Closing the account is the move that can raise your utilization ratio and eventually shorten your average account age.
Will I lose my points if I downgrade instead of closing?
No. A downgrade inside the same rewards family keeps the balance intact — Membership Rewards stay in your rewards account, Ultimate Rewards move with the account. The thing to watch is transferability rather than survival: downgrading a Sapphire to a Freedom card keeps the points but removes access to airline and hotel transfer partners unless you hold another Sapphire or Ink Preferred to pool them into.
How long do I have to get the annual fee refunded?
Chase is about 30 days from the fee posting for either a cancellation or a downgrade. Amex refunds in full if you notify it of a voluntary closure within 30 days of the closing date of the statement carrying the fee, and prorates product changes at any point in the year. Capital One is commonly reported around 39 days but is inconsistent, and Citi is about 37 days with no proration afterward.
Does closing a card lower my Chase 5/24 count?
No. Chase counts personal credit cards opened at any bank in the past 24 months, and an account you opened and later closed still counts until 24 months after its open date. A product change usually does not add to your count, but it does not remove anything either, and Chase has never officially published the rule.
Can I downgrade the Amex Platinum to a no-annual-fee card?
Not within the Platinum’s card family. Amex restricts product changes to compatible cards in the same family, which for the Platinum means the Gold at $325 or the Classic Green at $150. If you want a $0 way to keep Membership Rewards alive and transferable, the usual answer is holding the no-annual-fee Blue Business Plus alongside it.
If I downgrade my Sapphire Reserve, can I reapply later for the bonus?
Probably not on the same card. Chase’s current Sapphire terms say the bonus may not be available if you previously held the card or already received its bonus, and the old 48-month reset is gone. You can, however, earn the other Sapphire card’s bonus if you have never earned it, and Chase shows an eligibility pop-up during the application before any hard pull.
Should I transfer my points to an airline before closing a card?
Only if you have a specific redemption in mind. Flexible points in Chase or Amex do not expire while an eligible account is open, but airline and hotel programs run their own expiration clocks, and transfers are one-way. Moving a balance to a partner you rarely use trades a safe currency for one you may lose.
Bottom Line
A posted annual fee is a prompt to run three steps in order, not a reason to panic-close an account you spent years building. Ask for the retention offer, because the reported range on these two cards runs from $100 to $400 in credits and up to 50,000 points. If the answer is unsatisfying, product-change into a cheaper card in the same family and keep your points, your credit line and your history. Close only when you hold a second card in the same currency and the balance is already safely parked there — and if you only remember one thing from this guide, make it that Amex forfeits your Membership Rewards the moment the last linked card goes.